
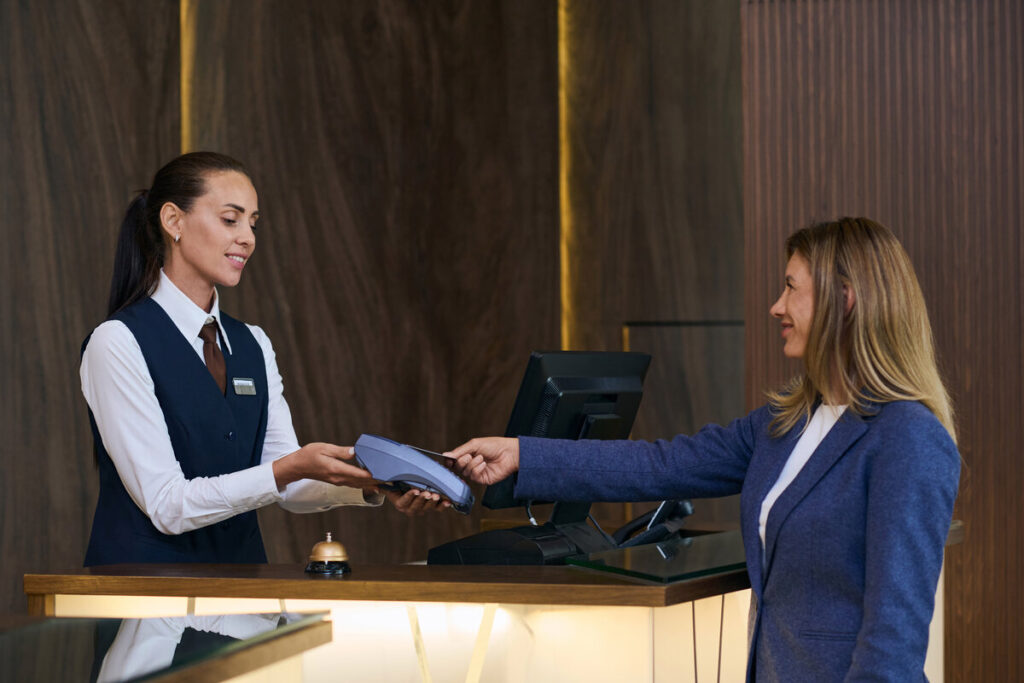
You hand over your card in a Dubai mall or a Paris café, and the machine asks a simple question: pay in the local currency or in rupees? Choosing rupees feels safer because you see the exact amount. But that comfort can cost you anywhere from about 2% to as much as 18% extra. Here is how to check the math in a few seconds before you tap.
What the card machine is really offering you
That “pay in your home currency” screen has a name: dynamic currency conversion, or DCC. The terminal reads the first six digits of your card, works out which country issued it, and offers to convert the bill into your home currency on the spot.
The catch is who does the converting. With DCC, it is not your bank or the card network. It is a third-party operator working with the merchant, and the merchant, its bank or the ATM operator usually add their own markup on top of the normal exchange rate. In documented cases, that markup is sometimes as high as 18%.
If you refuse and pay in the local currency, your card issuer handles the conversion instead. In Visa’s case, the conversion is done at the wholesale rate plus a 1% charge, and your bank may add its own foreign transaction fee on top (some banks charge nothing extra, some charge around 3%).
The 10-second formula to spot the hidden markup
The DCC screen has to show you the exchange rate it is using. Compare it with a reference rate (the one your banking or currency app shows at that moment):
Hidden markup (%) = (DCC rate ÷ reference rate − 1) × 100
If you only see the final amount in rupees, divide it by the bill in local currency to get the rate first.
A real receipt, worked through
One documented test shows it clearly: the same £6.90 purchase paid twice in a row with a Visa card in euros.
- With DCC: the customer was charged €8.20, at a rate of 1.1882 (interbank rate plus a disclosed 2.95%).
- Without DCC: the card issuer converted it at 1.16522, so €8.04.
Run the formula: 1.1882 ÷ 1.16522 = 1.0197, so DCC cost about 2% more on that small purchase. Notice that the “no DCC” route was not free either: working backwards, the interbank rate was about 1.1541 (1.1882 ÷ 1.0295), and the issuer’s 1.16522 sits roughly 1% above it, in line with Visa’s charge.
What that means on a bigger bill
Now take a hotel bill of €200, and suppose the reference rate that day is ₹90 per euro (an illustrative number, not today’s rate). The base cost is 200 × 90 = ₹18,000.
- Card route with a 1% conversion charge: ₹18,180, plus any fee your own bank adds
- DCC with a 2.95% markup, like the receipt above: ₹18,531
- DCC with an 18% markup, the worst case cited: ₹21,240
And if the machine shows ₹19,080 instead? 19,080 ÷ 200 = 95.4 per euro, and (95.4 ÷ 90 − 1) × 100 = a 6% hidden markup, or ₹1,080 more than the base cost before any bank fee.
Mistakes travellers often make
Assuming rupees means no fees. Some card issuers still charge a foreign transaction fee on DCC payments, even though they are billed in your home currency. You can end up paying both the DCC markup and your bank’s fee.
Thinking “decline” cancels an ATM withdrawal. Visa has allowed DCC at ATMs since 13 April 2019, and Mastercard does the same. The screen often looks like “accept this rate or not”, but refusing does not stop the withdrawal: the cash still comes out, just without the DCC commission.
Not knowing you can push back. Visa’s rules say a merchant must “Inform the Cardholder that DCC is optional and not use any language or procedures that may cause the Cardholder to choose DCC by default”. If you were converted without being given the choice, Visa’s chargeback reason code 76 covers exactly that situation, so raise it with your bank.
There is one honest exception: in a few specific cases, such as small cash withdrawals where the local-currency route carries a fixed fee, DCC can work out cheaper. That is why running the formula beats any blanket rule. As a default, though, paying in the local currency is usually the cheaper choice, and a quick division at the counter tells you for sure.